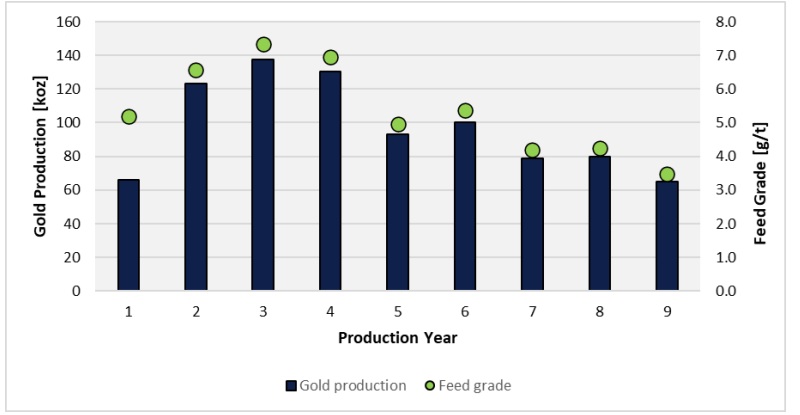
Heliostar Metals (HSTR.V) has released a progress update on its Ana Paula feasibility study. The updated resource calculation is now in the final stages and this will include the data from just over 25,000 meters of additional drilling since the Preliminary Economic Assessment was published. The high-grade panel has now been traced over a 300 meter horizontal strike length, and is about 50-60 meters thick in its core. The down-plunge extension now reached 330 meters while the Expansion Zone now extends up to 200 meters down-plunge of the high-grade panel (and it remains open in all directions).
The company has also completed additional metallurgical test work on Ana Paula rock and initial results have been in line with the test work that supported the Preliminary Economic Assessment. The Ana Paula mineralization is amenable to be recovered using a standard grinding and flotation process, followed by bio-oxidation. The feasibility study will use a NSR-based cutoff value versus a gold value expressed in g/t, resulting in a variable cutoff model. This could pave the way for a higher production rate at Ana Paula, and Heliostar will ensure that the engineering phase of the feasibility study will be mindful of the option to further increase the throughput (subject to confirmation in the resource and feasibility study, of course). As it currently stands, Heliostar will be looking to upsize the plant to accommodate 2,000 tonnes per day versus the 1,800 tpd in the PEA. These circuits could then potentially be expanded to accommodate 2,500 tonnes per day.
The next twelve months will determine the future of Ana Paula, and Heliostar Metals still wants to make an investment decision in the summer of next year, which should result in first production before the end of 2028.
As a reminder, the 2024 PEA yielded an after-tax NPV5% of US$845M at a gold price of $3400 per ounce. Using $4000 gold, the NPV increases to US$1.1B. While we expect an inflation-related capex and opex increase, using a higher gold price in the base case economic scenario should compensate for those cost increases.
Disclosure: The author has a long position in Heliostar Metals. Heliostar is a sponsor of the website. This post is for educational purposes only; be mindful investing in junior mining stocks is risky and you may lose your entire investment if things go wrong. Please read the disclaimer.